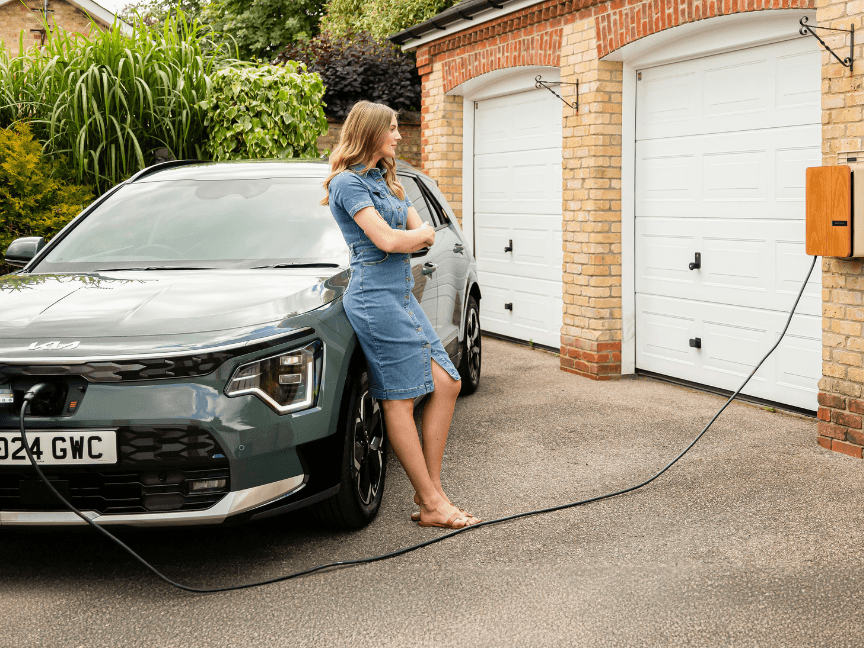
info@smh.group
  • Barnsley 01226 242 250
  • Buxton 01298 22108
  • Chesterfield 01246 274121
  • Harrogate 01423 524 322
  • Huddersfield 01484 541 155
  • Leeds (Garforth) 0113 286 2663
  • Leeds 0113 242 4677
  • Rotherham 01709 377 909
  • Sheffield 01142 664 432
  • Wakefield 01924 376 045
  • Wickersley 01709 701 116
  • Our Services
    • Accounting & Business Advisory
      • Accounting Services for Businesses
      • Bookkeeping Services for Businesses
      • Business Start-Up
      • Capital Allowances
      • Cloud Accounting
      • Company Secretarial and Legal Services
      • Contractors
      • Conveyancing
      • Financial Planning
      • Making Tax Digital for Income Tax
      • Other Tailored Services
      • Private Client
      • Restructuring and Recovery
      • R&D Tax Relief and Patent Box
      • Self-Assessment
      • Stamp Duty Land Tax Advisors
      • Tax Accountants & Tax Advisory Services
      • VAT Returns
      • Year End Accounts
    • Audit and Assurance
      • UK Limited Company Audit
      • UK Subsidiary Audit
      • Charity Independent Examination
      • Charity Audit
      • Assurance Reports
      • Grant Audit
      • Solicitors (SRA) Audits
      • UK Group Audit
    • Commercial Finance
      • Asset Finance
      • Bridging Loans
      • Business Loans
      • Development Finance
      • Invoice Finance
    • Corporate Finance
      • Business Valuations
      • Buying a Business
      • Case Studies
      • Due Diligence
      • Financial Forecasting
      • Grant Funding
      • Selling a Business
      • Strategic Planning
      • Transaction Tax Planning
    • Financial Services
      • Company Director Benefits
      • Employee Benefits
      • Our Client Service
      • Pensions & Retirement Planning
      • Personal Financial Solutions
      • Personal Investment Strategy
      • Protecting Those Who Matter
      • Taxation Planning
    • Payroll Services
      • Auto Enrolment
      • Payroll and Employee Services
      • Why Outsource?
    • Residential Mortgages
      • Buy To Let
      • First Time Buyers
      • Home Mover Mortgage
      • Stamp Duty Land Tax
    • Wills & Probate
      • Estate Tax Planning
      • Lasting Powers of Attorney (LPA)
      • Probate & Estate Administration
      • Wills, Trusts & Estate Planning
  • Our Locations
    • Barnsley
    • Buxton
    • Chesterfield
    • Harrogate
    • Huddersfield
    • Garforth
    • Leeds
    • Rotherham
    • Sheffield
    • Wakefield
    • Wickersley
  • Our Group
    • About SMH Group
    • Frequently Asked Questions
    • Testimonials
    • People
  • Blog
  • Careers
    • Current Vacancies
    • Core Behaviours
    • Staff Testimonials
    • Staff Benefits
  • Contact
  • Our Services
    • Accounting & Business Advisory
      • Accounting Services for Businesses
      • Bookkeeping Services for Businesses
      • Business Start-Up
      • Capital Allowances
      • Cloud Accounting
      • Company Secretarial and Legal Services
      • Contractors
      • Conveyancing
      • Financial Planning
      • Making Tax Digital for Income Tax
      • Other Tailored Services
      • Private Client
      • Restructuring and Recovery
      • R&D Tax Relief and Patent Box
      • Self-Assessment
      • Stamp Duty Land Tax Advisors
      • Tax Accountants & Tax Advisory Services
      • VAT Returns
      • Year End Accounts
    • Audit and Assurance
      • UK Limited Company Audit
      • UK Subsidiary Audit
      • Charity Independent Examination
      • Charity Audit
      • Assurance Reports
      • Grant Audit
      • Solicitors (SRA) Audits
      • UK Group Audit
    • Commercial Finance
      • Asset Finance
      • Bridging Loans
      • Business Loans
      • Development Finance
      • Invoice Finance
    • Corporate Finance
      • Business Valuations
      • Buying a Business
      • Case Studies
      • Due Diligence
      • Financial Forecasting
      • Grant Funding
      • Selling a Business
      • Strategic Planning
      • Transaction Tax Planning
    • Financial Services
      • Company Director Benefits
      • Employee Benefits
      • Our Client Service
      • Pensions & Retirement Planning
      • Personal Financial Solutions
      • Personal Investment Strategy
      • Protecting Those Who Matter
      • Taxation Planning
    • Payroll Services
      • Auto Enrolment
      • Payroll and Employee Services
      • Why Outsource?
    • Residential Mortgages
      • Buy To Let
      • First Time Buyers
      • Home Mover Mortgage
      • Stamp Duty Land Tax
    • Wills & Probate
      • Estate Tax Planning
      • Lasting Powers of Attorney (LPA)
      • Probate & Estate Administration
      • Wills, Trusts & Estate Planning
  • Our Locations
    • Barnsley
    • Buxton
    • Chesterfield
    • Harrogate
    • Huddersfield
    • Garforth
    • Leeds
    • Rotherham
    • Sheffield
    • Wakefield
    • Wickersley
  • Our Group
    • About SMH Group
    • Frequently Asked Questions
    • Testimonials
    • People
  • Blog
  • Careers
    • Current Vacancies
    • Core Behaviours
    • Staff Testimonials
    • Staff Benefits
  • Contact
Nov 18

Electric cars: the 100% first-year allowance ends in April 2027

  • November 18, 2026
  • SMH Accounting & Business Advisory

If your business is thinking about buying a new electric car, the next few months matter.

The 100% first-year allowance for new and unused zero-emission cars ends in April 2027, and the Autumn Budget on 28 October 2026 did not extend it again.

This allowance lets you deduct the full qualifying cost from your taxable profits in the year of purchase. After the deadline, relief will be spread over several years. A further reduction in the writing-down allowance means businesses will receive that relief more slowly.

Understanding the deadlines now can help you plan your purchase and its effect on business cash flow.

When does the electric car first-year allowance end?

The 100% first-year allowance stops for expenditure incurred:

  • On or after 1 April 2027 for companies paying Corporation Tax.
  • On or after 6 April 2027 for sole traders and partnerships paying Income Tax.

The Autumn Budget 2025 extended the allowance for a further 12 months. The Autumn Budget 2026 did not renew it.

The 100% first-year allowance for electric vehicle chargepoints has the same end dates.

What tax relief replaces it?

Electric cars bought after the deadline will enter the main capital allowances pool. Businesses will then claim writing-down allowances on a reducing-balance basis, receiving relief on part of the remaining balance each year.

Cars cannot qualify for the Annual Investment Allowance, full expensing or the main-rate first-year allowance, so these do not provide another route to upfront relief.

The main writing-down allowance fell from 18% to 14% in April 2026. The Autumn Budget 2026 announced a further reduction to 12% from 1 April 2027 for Corporation Tax and 6 April 2027 for Income Tax.

Accounting periods spanning the change will use a blended rate.

Example: buying a £50,000 electric company car

This example assumes a company paying Corporation Tax at 25%, with 12-month accounting periods. The later purchase falls in an accounting period beginning on or after 1 April 2027.

Qualifying expenditure incurred by 31 March 2027 Qualifying expenditure incurred from 1 April 2027
Allowance claimed in year one £50,000 £6,000
Tax saved in year one £12,500 £1,500
Tax saved in year two £0 £1,320
Tax saved in year three £0 £1,162

The total relief over the car’s life is broadly the same, but after the deadline it is received over many years. In this example, £11,000 of tax relief moves out of year one.

Companies paying the 19% small profits rate, or receiving marginal relief, will see different figures.

Our capital allowances team can help you understand what the change means for your business.

Who is affected?

The effect depends on the vehicle and how your business acquires it:

  • Businesses buying new electric cars: companies, sole traders and partnerships buying outright or through hire purchase are affected.
  • Sole traders and partners with private use: relief remains restricted to the business proportion of the car’s use.
  • Used electric cars: these have never qualified for the 100% first-year allowance, so the withdrawal does not change their eligibility.
  • Electric vans: these are not treated as cars for capital allowances. They remain eligible for the Annual Investment Allowance, so most businesses can continue to claim full relief upfront.
  • Leased electric cars: these are not affected by the withdrawal because there is no capital expenditure on buying the vehicle. Lease rentals on zero-emission cars remain deductible without the 15% restriction that applies to higher-emission cars.
  • Company car drivers: this measure does not directly change the benefit-in-kind treatment of electric company cars.

Timing matters: delivery dates, orders and deposits

The deadline depends on when expenditure is incurred, rather than simply when you place an order or pay a deposit.

The relevant date depends on the purchase agreement:

  • Outright purchase: expenditure is generally incurred when the obligation to pay becomes unconditional, usually on delivery. If payment is not due until more than four months later, the payment due date applies instead.
  • Hire purchase: relief generally follows the car being brought into use, so it needs to be delivered and brought into use before the relevant deadline.

With lead times on some models running to several months, an order placed in February may not qualify in time. If delivery is expected close to the deadline, check the contract and payment terms before signing.

What should your business do now?

If an electric car purchase is already part of your plans, consider the following:

  • Review the timing of planned purchases. Buying before the deadline could mean receiving thousands of pounds of tax relief a year or more earlier.
  • Check delivery dates and payment terms. Confirm when the dealer expects to deliver the car and when payment becomes due. An order date alone does not secure the allowance.
  • Compare buying with leasing. Once upfront relief ends, the gap between owning and leasing narrows. Leasing may also suit your cash flow better.
  • Consider the whole picture. Benefit-in-kind, salary sacrifice and mileage allowances all affect whether a company car is right for you. Tax relief should support a sensible purchase, rather than be the sole reason for buying.

Talk to SMH Group before your next vehicle purchase

If you are considering an electric car for your business, we can help you understand the tax relief, compare your options and plan around the relevant deadlines.

Speak to your usual SMH Group contact or get in touch with our team. We will help you get the timing right.

  • Facebook
  • Twitter
  • LinkedIn
  • E-Mail

Comments are closed.

Categories

  • Accounting & Business Advisory
  • Audit & Assurance
  • Barnsley
  • Buxton
  • Careers
  • Chesterfield
  • Commercial Finance
  • Corporate Finance
  • Departments
  • Financial Services
  • Harrogate
  • Leeds
  • Payroll Services
  • Renishaw
  • Residential Mortgages
  • Rotherham
  • Sheffield
  • SMH Accounting & Business Advisory
  • SMH Audit & Assurance
  • SMH BCL Accountants
  • SMH BullockWoodburn
  • SMH Capital Allowances
  • SMH Commercial Finance
  • SMH Contractors
  • SMH Conveyancing
  • SMH Corporate Finance
  • SMH Financial Services
  • SMH Group
  • SMH Haywoods
  • SMH Howard Matthews
  • SMH Jolliffe Cork
  • SMH Mitchells
  • SMH Payroll & Pensions
  • SMH Residential Mortgages
  • SMH Sheards
  • SMH Staff Testimonials
  • SMH Sutton McGrath Hartley
  • SMH Tax Advisers
  • SMH Wills & Probate
  • Wakefield
  • Wills & Probate
ACCA
Xero Platinum Champion Partner
SMH Chartered institute

Our Services

  • Accounting & Business Advisory Services
  • Audit and Assurance Services
  • Commercial Finance & Commercial Finance Brokers
  • Corporate Finance
  • Financial Advice & Personal Financial Planning
  • Payroll Services
  • Residential Mortgages Services
  • Wills & Probate Services

info@smh.group

Careers

Social

  • Facebook
  • Linkedin
  • Instagram
SFSY EU

SMH Group Head Office

Unit 19, Ravenshorn Way, Renishaw, Derbyshire, S21 3WY

0330 1070 873

SMH Sutton McGrath Hartley

5 Westbrook Court, Sharrow Vale Road,
Sheffield, S11 8YZ

01142 664 432

SMH Bullock Woodburn

Norfolk House, Hardwick Square North,
Buxton, Derbyshire, SK17 6PU

01298 22108

SMH Haywoods

24-30 Mansfield Road,
Rotherham, S60 2DT

01709 377 909

SMH BCL Accountants

2 Pavilion Business Park, Royds Hall Road, Lower Wortley,
Leeds, LS12 6AJ

01132 424 677

SMH Jolliffe Cork

33 George Street
Wakefield, WF1 1LX

01924 376 045

SMH Howard Matthews

Queensgate House, 23 North Park Road, Harrogate, North Yorkshire, HG1 5PD

01423 524 322

SMH Howard Matthews

Lidgett House, 56 Lidgett Lane, Garforth, Leeds, West Yorkshire,  LS25 1LL

01132 862 663

SMH Sheards

Vernon House, 40 New North Road, Huddersfield HD1 5LS

01484 541 155

SMH Reed Smith

Copia House, Great Cliffe Court, Great Cliffe Road, Dodworth, Barnsley, S75 3SP

01226 242 250

SMH Mitchells

91-97 Saltergate,
Chesterfield, S40 1LA

01246 274 121

SMH Parkins

Moor Park House,
Clifford Lister Business Centre,
Bawtry Road, Wickersley,
Rotherham, S66 2BL

01709 701116

Official Information | Legals | Privacy Policy | Cookie Policy | Terms of Use | Terms of Business