
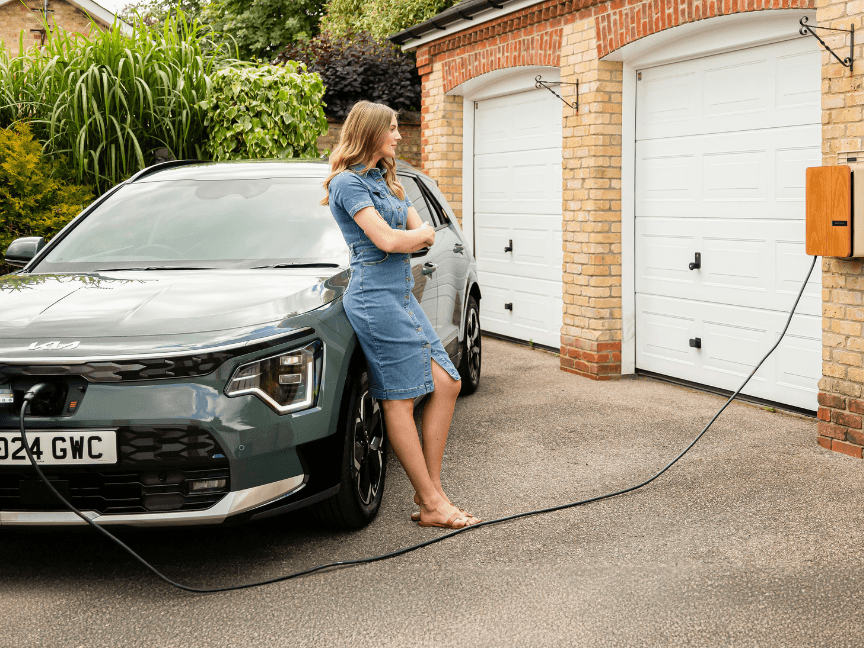
The Autumn Budget 2026 included around 100 tax measures, but it did not extend the 100% first year allowance for electric cars. As a result, businesses buying a new electric car from April 2027 will receive a much lower initial tax deduction.
Currently…
Until 31 March 2027 (5 April 2027 for sole traders and partnerships), there is effectively full expensing when purchasing a new electric car. For example, if a partnership spends £75,000 on two new electric cars for its employees, the partnership’s profit will be reduced by £75,000, saving tax and national insurance contributions (NICs) of £31,500, if the partners are higher rate taxpayers.
Should the car be for the use of a sole trader or partner, then the deduction is restricted based on the proportion of non-business use. So, if the two electric cars were for partners, with 30% of the mileage for private purposes, then the deduction would have been £75,000 x 70% = £52,500.
From April 2027
From 1 April 2027 (6 April 2027 for sole traders and partnerships), new electric cars will only qualify for the same writing-down allowance that is given for cars with CO2 emissions up to 50g/km:
- To make matters even worse, this writing-down allowance is being reduced from 14% to 12%.
- For the two employee electric cars, the deduction in the year of purchase will in future be just £9,000, saving £3,780 in tax and NICs for the partners.
- Unfortunately, cars do not qualify for the annual investment allowance or any of the other available first-year allowances.
For any business planning to purchase a new electric car, there is still time to do so while full expensing is still available. Electric cars will still carry an advantage from an employee’s tax viewpoint, although rising benefit-in-kind rates over the next few years will reduce the benefits.
HMRC’s guide to claiming capital allowances can be found here.
If your business is considering buying an electric car, it may be worth reviewing the timing before the tax relief changes take effect. Our team can help you understand the tax implications.
Visit our contact page, email info@smh.group or call 0330 1070 873.


Comments are closed.