
How much would it cost to increase the income tax personal allowance?
The personal allowance determines how much income you can receive before paying income tax. Since 2010, however, it has not applied universally because taxpayers with adjusted net income above £100,000 see their allowance gradually reduced, falling to zero at £125,140.
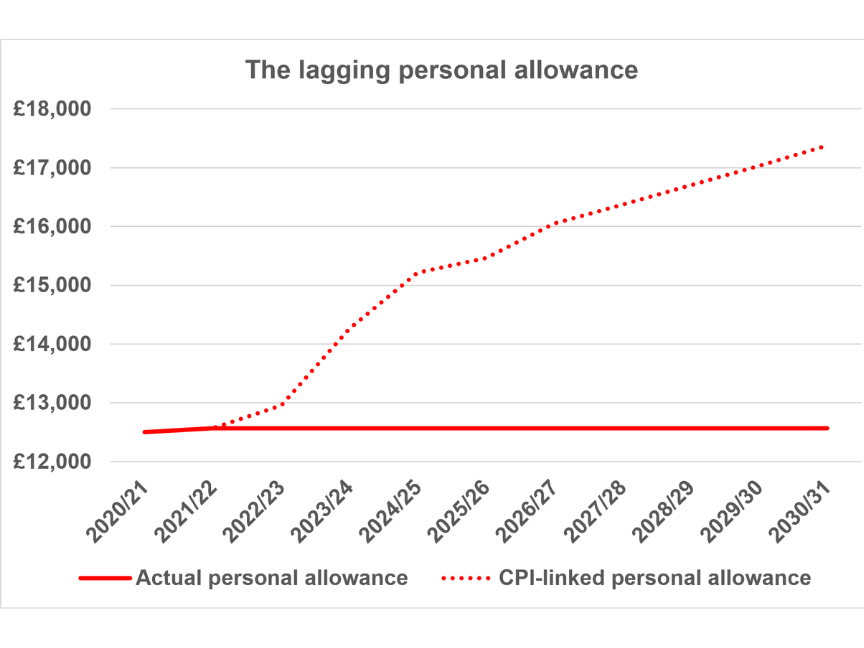
If you escape the taper, your personal allowance is £12,570, a figure that has been unchanged since April 2021, when then Chancellor, Rishi Sunak, froze it for five years. Before Sunak’s fix, the personal allowance had usually been increased by at least the rise in consumer price index (CPI) inflation. Two of Sunak’s five successors have extended the freeze, which is now due to end in April 2031.
As stealth taxes go, freezing the personal allowance was seen as an easy option:
- A Chancellor can state that they are not increasing taxes because they are not cutting the allowance.
- The reality is that taxes are being increased by inflation eroding the buying power of the allowance.
The stealth effect is beginning to wear thin as the rising slice of their earnings lost to tax becomes obvious to many, acknowledged by the Prime Minister as a doorstep topic during his by-election.
Perhaps more than coincidentally, the Institute for Fiscal Studies (IFS) has been looking at how much it would cost to unfreeze the personal allowance. As it would be far too costly to make good the losses since 2021, the IFS considers the option of reinstating indexation from 2027/28. This is not quite as simple as it seems because the personal allowance currently also fixes national insurance and higher rate tax thresholds, raising the question of whether they should also increase. If they are unchanged, then the long-term cost of restoring indexation is £6.7 billion a year, not much less than the cutting of basic rate tax to 19%.
The tightness of the government’s finances implies the £6.7 billion would have to be replaced by higher taxes elsewhere (or, possibly, higher borrowing). All of which means that tax planning, rather than the Chancellor, is the more likely route to cutting your tax bill.
For more information, get in touch with us by calling 0114 266 4432 or email info@smh.group for more information.
Tax treatment varies according to individual circumstances and is subject to change.
The Financial Conduct Authority does not regulate tax advice.


Comments are closed.